A commitment needs an operating counterpart
A sustainability objective becomes an operational question when someone must decide which supplier, material, route, packaging format or investment to choose. That decision needs a boundary, relevant evidence and an accountable owner. A statement of ambition does not provide those elements by itself.
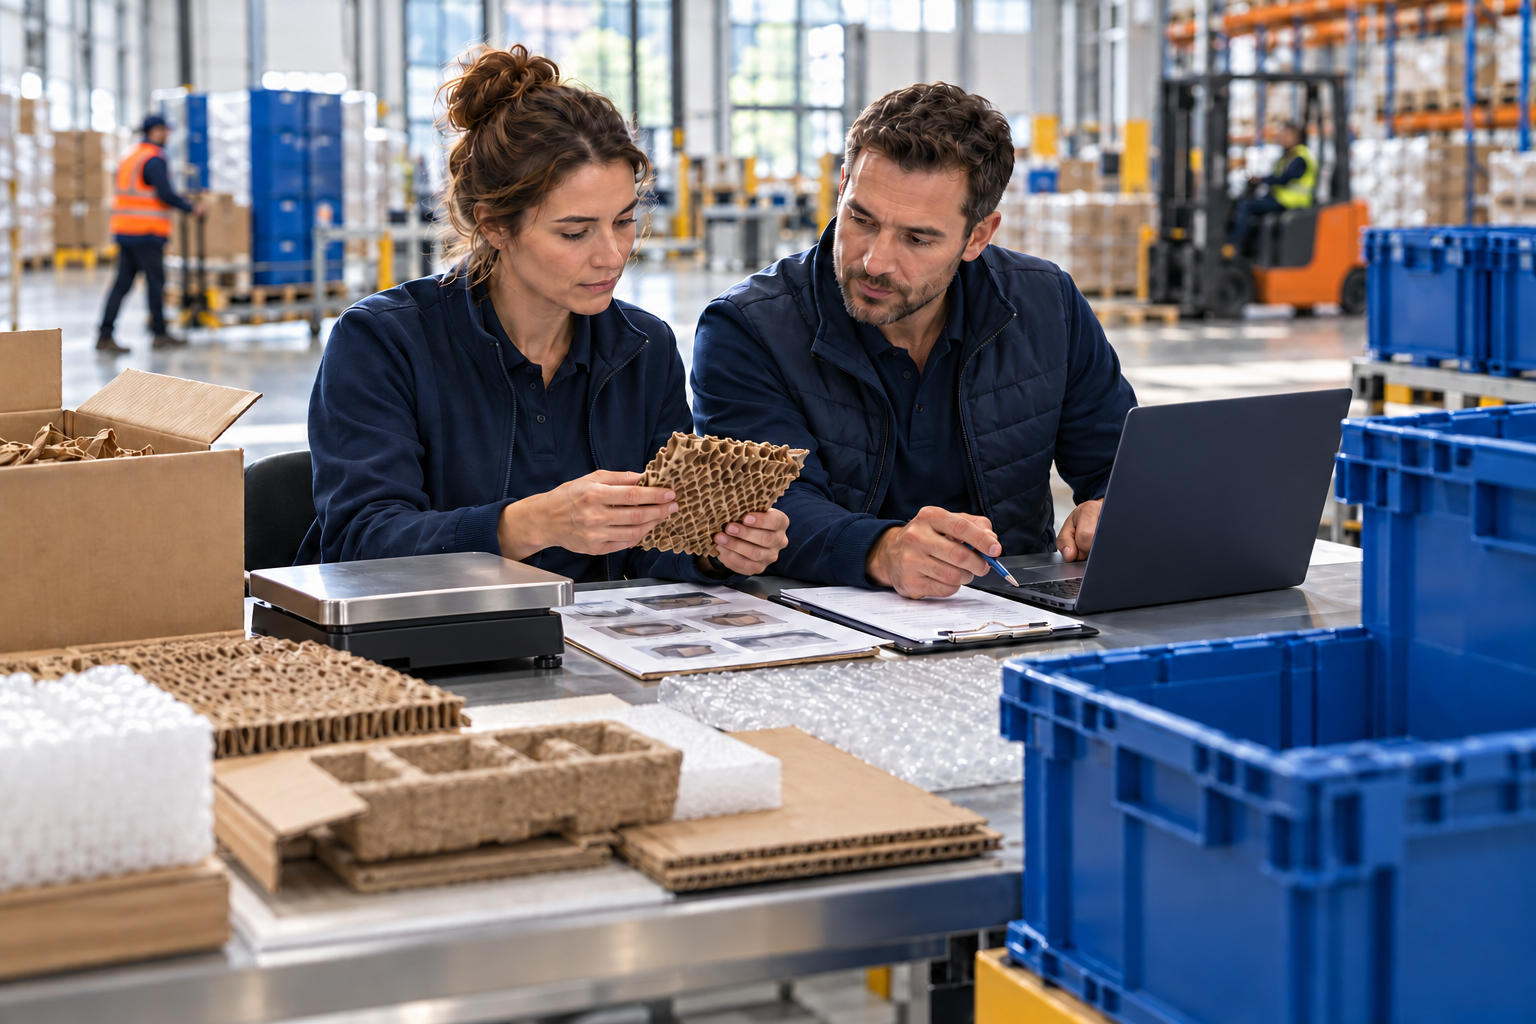
Our proposed approach starts with one question that a team can examine, such as packaging choices for an agreed product flow. Establish what the records show, what remains unknown and which changes are feasible before claiming an environmental benefit.
What the research says and what it does not
MIT’s 2026 report draws on 1,810 responses from professionals across 91 countries and examines how sustainability commitments translate into governance and operating decisions. MIT discloses external sponsors for the work. It is a survey of respondent experience, not an audit of every participating organisation’s environmental outcomes. [1]
MIT’s accompanying release describes a gap between stated ambition and accountability, and reports an association between cross-functional teams and sustainability being embedded in decisions. The release and report describe the same study; they are not two independent confirmations. The association should not be treated as proof that introducing a team will produce a particular emissions reduction. [2]
Define the evidence boundary
Agree the product, flow, supplier group, time period and decision under review. Record where the data comes from, who owns it and what it leaves out. Weight, material type, movement distance and energy use can require different collection methods and specialist interpretation.
A missing value should remain visible as a gap. Where estimates are used, document the method and assumptions. Improving record completeness is useful, but it is different from reducing waste or emissions.
Use traceability for the right question
Operational traceability sits within the Control Tower principle: linking orders, stock, supply and delivery events to understand exceptions and responses. Sustainability evidence may build on those links while adding material provenance, environmental factors or supplier records.
Knowing where a product moved does not by itself establish ethical sourcing or environmental performance. Keep those claims tied to the evidence required for the specific question. Formal accounting, legal advice, certification and independent assurance call for appropriate specialist input.
Measure the result and its trade-offs
- Evidence coverage: which suppliers, products or flows have usable records?
- Operating change: what material, energy, handling or transport activity actually changed?
- Comparison: are baseline and follow-up periods comparable in volume, mix and boundary?
- Trade-offs: did service, cost, damage or activity elsewhere change at the same time?
- Ownership: who checks the evidence and approves any public claim?
Start with a decision that can be reviewed
A bounded trial can connect an operating change to a measurable result without assuming that a new technology or shorter route automatically improves the overall environmental outcome. Review the method with relevant specialists and keep uncertainty visible.
A Sustainability Evidence Discovery Workshop can define the evidence boundary, priority gaps and a proposed assessment. SCP’s proposed service supports evidence mapping and operational improvement; it does not imply independent assurance or guaranteed environmental savings.
Sources and evidence notes
Sources checked on 17 October 2026. Research findings and company reports are attributed above; practical recommendations are SCP’s interpretation. The examples do not imply endorsement, partnership or SCP client results.
- MIT State of Supply Chain Sustainability Report 2026 ↗
2026 report. Professional survey; sponsor support disclosed by MIT.
- MIT Sustainability report findings on commitment and governance ↗
23 September 2026. Publisher summary of the same survey; not independent corroboration.
Explore the next step
Discuss a defined supply-chain challenge and agree the evidence needed for a useful decision.
Workshop format and any fees are agreed before booking. Follow-on work requires a separate scope and business agreement.